Military
Real Estate.
You protect our lives. We protect your money.
$99 to sell · Up to 2% credit back when you buy.
Proven results.
Huge savings.
Hassle-free.
Real homes. Real people. Real savings with Beycome.
 Sold 09/24/2026
5415 Andover Dr
Tyler, TX
 Sold 09/24/2026
19044 Inndale Dr
Lakeville, MN
 Sold 09/24/2026
804 N Maple St
Springfield, GA
 Sold 09/24/2026
14 Seaside Ln
Greer, SC
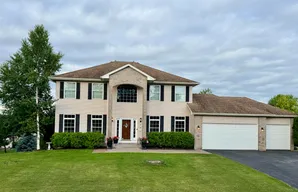 Sold 09/24/2026
22301 Jasmine Way
Rogers, MN
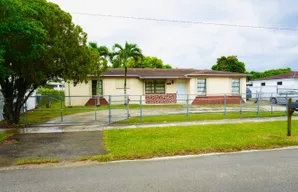 Sold 09/23/2026
25410 SW 127th Ave
Homestead, FL
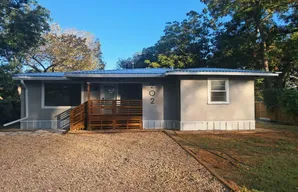 Sold 09/23/2026
202 Jones St
Smithville, TX
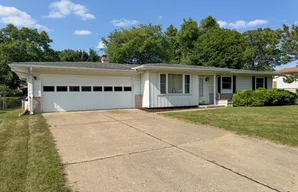 Sold 09/23/2026
4176 Pomeroy Ave
Waterford Township, MI
 Sold 09/23/2026
31475 Cabana Rye Ave
San Antonio, FL
 Sold 09/23/2026
18030 66th Ct APT 2N
Tinley Park, IL
 Sold 09/23/2026
2110 Colony Dr SW
Huntsville, AL
 Sold 09/22/2026
411 S Higby St
Jackson, MI
Sold 09/24/2026
5415 Andover Dr
Tyler, TX
Sold 09/24/2026
19044 Inndale Dr
Lakeville, MN
Sold 09/24/2026
804 N Maple St
Springfield, GA
Sold 09/24/2026
14 Seaside Ln
Greer, SC
Sold 09/24/2026
22301 Jasmine Way
Rogers, MN
Sold 09/23/2026
25410 SW 127th Ave
Homestead, FL
Sold 09/23/2026
202 Jones St
Smithville, TX
Sold 09/23/2026
4176 Pomeroy Ave
Waterford Township, MI
Sold 09/23/2026
31475 Cabana Rye Ave
San Antonio, FL
Sold 09/23/2026
18030 66th Ct APT 2N
Tinley Park, IL
Sold 09/23/2026
2110 Colony Dr SW
Huntsville, AL
Sold 09/22/2026
411 S Higby St
Jackson, MI
Built for the people who
protect our country
Sell before your PCS.
Keep your equity.
When orders come in, you need to sell fast — not spend months negotiating a 6% commission. With beycome, you list on the MLS for $99 flat. No listing agent. No percentage taken from your proceeds.
On a $400,000 home, a traditional 3% listing commission costs $12,000. With beycome, you pay $99 and keep the rest.
- Listed on MLS within 24 hours
- Professional photography coordinated for you
- Yard sign shipped to your door
- Offer management support, fully remote
- Military clause support for lease/sale agreements
- Cancel anytime — no penalty if orders change
Your VA benefit +
our 2% credit = maximum savings
VA loans already give you $0 down, no PMI, and competitive rates. Stack that with beycome's 2% buyer credit at closing and you've unlocked the most powerful home-buying combination available to military families.
That 2% credit can cover closing costs, lower your loan balance, or go straight back into your pocket — your choice.
- $0 down payment with VA loan eligibility
- No private mortgage insurance (PMI)
- Up to 2% credit back at closing via beycome
- Search every MLS listing near any base nationwide
- BAH-aligned price filters built in
- Remote offer submission — buy from anywhere
How it works
Designed for military timelines — fast, remote, and straightforward.
To sell
Enter your property details
Address, photos, description — about 15 minutes online. Our team reviews it and switches your listing on. Nobody knows your home like you do.
Go live on the MLS
Your listing hits the MLS within 24 hours and syndicates to Zillow, Realtor.com, Redfin and hundreds more — automatically, for a flat $99. It runs for 24 months (12 months in MD & PA).**
Manage offers from anywhere
Offers land in your dashboard. Accept, counter or reject in one click — from base, from overseas, from your phone at 0400.
Close and keep your equity
No listing commission, documents signed electronically, closing tracked online. On a $450,000 home, skipping a traditional 6% commission keeps up to $27,000 of your equity where it belongs.*
To buy
Get pre-approved for a VA loan
Put your entitlement to work and buy with $0 down. We connect you with VA-approved lenders who already understand military income, BAH and PCS timelines.
Search homes near your base
Every active MLS listing in the country, filtered the way you actually need it: commute to base, price, school district.
Submit your offer
Together, we analyze and submit your offer, then guide you through inspections, financing, and closing.
Get 2% back at closing
Up to 2% of the purchase price credited back at closing — about $9,000 on a median-priced U.S. home.* Put it toward closing costs, buy your rate down, or just keep it.
*Estimated savings are based on your estimated home value and a traditional 6% total commission; estimated “cash back” is based on the US average home price and a traditional 3% buyer-agent commission. Actual amounts may vary based on transaction terms, market conditions, lender requirements, and applicable state law.
**Georgia MLS requires a $25 cancellation fee. Listings under contract cannot be canceled.
You earned these benefits.
Use every one of them.
The VA home loan benefit is one of the most powerful financial tools available to service members, veterans, and eligible surviving spouses. Here's what you get:
- No down payment required — finance 100% of the home's value
- No private mortgage insurance (PMI) — saves hundreds per month
- Competitive interest rates — typically lower than conventional loans
- Closing cost limitations — VA limits what sellers can charge
- No prepayment penalty — pay off early at no cost
- Reusable benefit — use it again after each PCS move
Eligibility: 90 days active duty in wartime, 181 consecutive days in peacetime, 6+ years in National Guard or Reserves, or surviving spouse of a service member who died in the line of duty.
Your BAH covers it.
Your rights protect it.
The Basic Allowance for Housing (BAH) you receive can count toward your loan qualification — lenders treat it as regular income. That means you may qualify for a larger loan than you think, with your housing covered by the military before your first paycheck.
Beyond financing, two powerful protections have your back:
- Servicemembers Civil Relief Act (SCRA) — caps interest rates at 6% on pre-service obligations, prevents foreclosure without a court order, and lets you break leases penalty-free with PCS orders.
- Veterans Affairs (VA) Loan Servicing — if you ever face financial hardship, VA works directly with your lender on your behalf to prevent foreclosure.
Buying near a new base?
Start here.
PCS moves give you weeks, not months. Beycome's online platform means you can tour virtually, submit offers remotely, and close electronically — all before you physically arrive at your new duty station.
When evaluating homes near a base, prioritize:
- Commute distance to the gate — factor in traffic during PT hours
- School district ratings — critical if family is moving with you
- Resale timeline — average days on market in that zip code
- Rental potential — can you rent it out at your next PCS move?
- HOA rules — some restrict short-term or military tenant subleasing
- Flood zone / hazard disclosures — know before you close
Moving every 3 years?
Make each move count.
The average military family moves 9 times during a service career. Instead of renting and building no equity, each PCS move can be an opportunity to buy, build equity, and sell at a profit — especially with no down payment required on VA loans.
DoD relocation assistance covers many of your costs:
- DPS (Defense Personal Property System) — government-funded household goods shipment
- DLA (Dislocation Allowance) — covers incidental moving expenses
- TLE (Temporary Lodging Expense) — up to 10 days lodging covered on both ends
- MALT (Monetary Allowance in Lieu of Transportation) — mileage reimbursement for driving your POV
Add beycome's $99 listing fee and 2% buyer credit to the equation and you're keeping more of your money at every stop.
Ready to sell for $99
or buy with 2% back?
Thousands of military families have saved millions in commissions with beycome. Join them — it takes 15 minutes to get started.
The military homeowner’s playbook.
Renting, selling, pricing, and moving — the parts of a PCS nobody hands you a checklist for.
Renting out your military home
Sometimes while you’re in service, you get deployed or relocated. If this happens and you’re renting your place, you have one of two options: try to break your lease, or sublet.
Subletting is the process of subleasing a property to someone else under your lease. Before you decide to do this, speak with your landlord to confirm they allow it.
If you’re renting out your house, start by establishing rent. This means researching and understanding your local real estate market. The price should reflect a combination of utilities, amenities, furnishings, nearby attractions, and the cost of homes that neighbor yours. Look closely at each of these so you don’t sell yourself short.
Trends change over time, so keep checking each factor throughout your renting journey and raise or lower your price accordingly.
Repair and renovate anything broken or outdated before someone moves in. It helps get you referrals and can raise your rent over time. Photograph everything as well, so at the end of a sublease you can charge for any damage.
Before anyone signs a lease, look into who they are. Prepare a series of relevant questions and meet them face to face. Check their credit score and any eviction reports to gauge whether they’re reliable renters, and ask for reference letters from previous landlords. Proof of income helps confirm they can pay on time.
Once you find a suitable subtenant, put the terms in writing. The lease should specify the rules, the amount owed each month, and the consequences if any term is broken. Add a military clause, which lets a renter know the lease can be broken at any time due to active duty orders.
State your requirements explicitly so you don’t run into problems while you’re away.
Selling military housing off-base
Selling a home takes preparation. Start by making sure you have enough money set aside to handle renovations and repairs on anything that needs work.
Sell through a listing agent and you give up roughly 3% of your sale price in commission. Sell the home yourself and you keep that money — often thousands of dollars.
Give yourself as much time as you can. Sell in a hurry and you settle for a lower price. With a longer runway you can negotiate properly and earn more in the end. Look up the average time a home in your area takes to sell, and plan around it.
The condition of the market matters just as much. If there’s little activity, consider waiting. When you choose to sell has a real impact on what you walk away with.
Pricing your military home for sale
To set your price, start with a Comparative Market Analysis (CMA) of homes similar to yours. A CMA shows the similarities and differences between houses around your size and value, so you can land on a realistic asking price.
As you compare houses, note any amenity a home has that yours could match. Attending open houses is also a good way to pick up selling techniques.
Once you have a list of improvements, contact an inspector who can tell you which repairs are necessary, then work through them in order of importance.
Trends worth matching include:
- Kitchen: buyers pay more for a modern kitchen. Look into current trends to see how yours could improve — islands, counters, cabinet styles, and lighting all count.
- Bathroom: bathrooms are a deal breaker in many final decisions. Updating counters, mirrors, shower heads, and lighting makes yours more desirable.
- Exterior: first impressions happen outside. Repaint where needed and fix holes and chips in the fence. In the yard, curb appeal reels people in — add seasonal plants, simple decor, and keep the grass in pristine condition.
- Roof: weather wears a roof down over the years. Have yours inspected, and repaired if needed, before you list.
When you write your listing, emphasize the strong points: malls, grocery stores, recreational facilities, schools, and anything else that draws buyers in.
Maintaining and decorating a military home for sale by owner
To sell your home, look at it through a buyer’s eyes. It helps to remember how the house looked when you bought it, and what convinced you to go through with the purchase.
For repairs, hire a professional to help you work out what actually needs doing. Plumbers, contractors, and handymen are worth the call.
The goal of selling is to make your home feel like a great place for someone else to start a life. Buyers need to picture themselves comfortable in it, and that usually means spending some of your savings on repairs and updates.
Decluttering, staging furniture, and finding your pets somewhere else to stay during showings all make a home feel more liveable.
Advertising military homes for sale by owner
To save the commission we mentioned earlier, list through a service that gets you on the MLS directly, such as beycome.
Write your ad plainly and say exactly what you’re selling. Lay out the facts, and show why your home is the better choice next to the others around it. Classifieds and social platforms are easy places to share the listing once it’s live.
Offline still works too: signs, posters, flyers, lawn signs, and word of mouth.
Military relocation services
As you plan your move, temporary or permanent, there are a number of things to line up so you’re ready to go.
Several organizations, such as Military Relocation Services, exist to make the process run more smoothly.
The Department of Defense reimburses service members for moving costs, and that assistance takes several forms. There’s a transportation allowance for the drive to your new duty station. Per Diem covers lodging and food along the way. The Dislocation Allowance (DLA) helps with the extra costs of a permanent move, and a Temporary Lodging Allowance (TLA) covers temporary housing.
The government also pays to ship your belongings, as long as they meet the weight requirements. Unaccompanied baggage is usually delivered separately after you arrive, but still counts toward your weight limit.
If you’d rather not move everything, storing your belongings while you’re on active duty or relocating can save you thousands. National operators like Extra Space Storage and Public Storage are a good starting point, but compare them against local units near your base or your current home — the best deal is often local.
Knowing what you’re entitled to makes moving, buying, or leasing far simpler and safer.